While these crypto interest updates have normally been posted on the first of each month, I thought it was important to share one as soon as possible. Unlike the previous updates, this one will also discuss the state of the greater industry more generally.
Summary
- If you don't read anything else in this post, the following sentence should tell you what you need to know. It's quite possible that there is now no major lender that has ever actually made a profit in the history of crypto lending, despite lenders having been around for five years.
- I will spend a great deal of time explaining why recent events make clear that there not only is, but has always been, a fundamental problem with the crypto lending industry.
- In a previous update, I said that crypto lending was "dead" for retail investors. Now, it is simply dead.
- Withdraw your money from all exchanges, lenders, and even vendor "custody" solutions to cold storage. The wallet security guide on this site can assist you if you've never done that before. Scroll down to the bottom section about cold wallets; the top sections are obsolete given current events.
- One of the reasons that lending had somewhat mitigated risk in the past was because it was, and remains, difficult for a typical user to store money in cold wallets and not lose it. That calculation has either changed or may always have been incorrect. Whatever the case, it is clearly now worth taking the moderate risk that you will lose your money by making a cold storage mistake.
- FTX is, by far, the worst crisis in the history of cryptocurrency. It is not another "China bans bitcoins" panic and represents a turning point. In addition to withdrawing money from lenders, seriously consider whether to simply sell all of your coins altogether and get out.
Profitability
Let's begin with a discussion of the profitability of lenders in the space. I'll provide a simple table here that lists the outcome to investors and/or depositors in select companies:
| Company | Outcome |
| Voyager | Losses of at least $1b, $600m of which passed onto depositors; bankruptcy case now reset with additional losses after buyer FTX fails |
| Celsius | $1.6b lost, plus total losses to equity investors |
| Genesis | $1.4b of losses passed onto parent company Digital Currency Group in just four months; likely was insolvent two separate times; fired 20% of staff and CEO, risk manager quit week before FTX issues |
| BlockFi | Filing for bankruptcy despite large amount of equity and massive backstop; 800 job losses |
| Ledn | Sold itself as the most risk-averse lender, then lent money to Alameda Research |
| Hodlnaut | Withdrawals are still paused; admitted losses from other lenders |
| FTX | Earn product failed along with everything else; no need to discuss further |
| Unsecured DeFi protocols | Almost every protocol facing loan defaults and losses |
| Secured DeFi protocols | Multiple hacks and thefts resulting in complete closure and losses passed onto contract users |
There are still a few companies out there that haven't announced losses, like Nexo, which nevertheless admitted that its balance sheet was valued with "less than" 10% company tokens ("less than" likely means 9.99% here,) and crypto.com, which hasn't said anything yet. Be warned that when there are company tokens involved, it's easy to say that there were no net losses if you increase the number or value of company tokens on the books.
The simple conclusion from this table is that now, I cannot identify a single company without company tokens that has made any money on crypto lending. And it's not like the table shows that the companies have lost small amounts of money doing productive things, as BlockFi was until this week by spending money building its technology and pursuing SEC registration. All of the losses and bankruptcies are a direct result of the lending business model.
Hopefully this table shows readers why my mind has changed dramatically in the past month. If you were looking to invest in typewriter manufacturers today, you don't look for the best typewriter company. You look at the past performance of the industry, whether there is anything that is expected to change that would affect future performance, and would eventually come to the conclusion that it's not possible to make money producing typewriters. Therefore, it wouldn't make sense to lend money to any typewriter company even if it performed better than other typewriter companies.
Similarly, there's no reason to lend money to a crypto lender when events have shown that nobody has actually earned any profit in the industry. Even in the miracle outcome that no more money is lost, there's nothing stopping the lenders from finally recognizing that lending is unprofitable and using bankruptcy as an easy out.
Why crypto lending is untenable
It's pretty clear that crypto lending is a huge money sink, and that might be all one needs to know to not get involved in it. But I'll still try to figure out why crypto lending is untenable, even if that really doesn't affect anyone who wants to start a lending company.
Note that I still can't reveal everything that I learned in September due to non-disclosure agreements, but since I am slowly unwinding my exposure in cryptocurrency, I no longer care about making "enemies" in the lending industry, which allows me to reveal things that are legal but not honorable about the other companies. As to BlockFi, I don't think they're going to be suing me any time soon.
My theory is that crypto lending fails because it is not possible for a human to accurately detect scams in cryptocurrency. When I was investigating to whom to lend money in September, I had a video call with John Glover, the risk manager at Ledn. Glover's image is featured on Ledn's website on this page and there is a full-page ad prominently featuring Glover and touting Ledn's risk management principles. Glover worked in traditional finance managing loan risk before working at Ledn.
In the video call, Glover attempted to sell me on a loan to Ledn, saying that he could reveal that he lent money only to the most trustworthy firms, like Alameda Research. He explained that Alameda was performing "market-neutral" trading strategies, and the high quality of Alameda as a borrower explained why Ledn could only offer lower interest rates compared to BlockFi. Glover and Mauricio Di Bartolomeo spent a significant amount of time in the call criticizing Genesis and BlockFi for losing money in the previous 3 Arrows disaster, and stating that I should work with Ledn despite the low rates because, among other things, Alameda was a trustworthy borrower. This call was conducted in September, almost a year after FTX had begun its lending of customer deposits to Alameda. As late as last Tuesday, the day FTX was falling apart, Ledn was apparently still replying to support tickets stating that they believed Alameda was good for their money.
Ledn's employees are honest and extremely smart, and Mauricio is obviously trying to run an ethical business. Yet Glover himself was still scammed by Bankman-Fried despite his decades of experience in the financial industry. I assert that if John Glover failed to identify Alameda as a risky borrower, then those who claim to have "seen this coming" and avoided Alameda and FTX were simply lucky and are trying to make themselves appear smart after the fact.
For another example, look at 80,000 hours, which has at least five full page articles praising Sam Bankman-Fried and how he has devoted his life to giving to charity. The organization seems to be in such disbelief that it shamefully hasn't even taken them down, instead adding a short message box stating that it is "monitoring the situation." 80,000 hours is an organization whose sole purpose is to perform research and make recommendations about how to make the most impact on the world, and somehow this article misled people for 8 years! If even a few people followed 80,000 hours's advice on Fried and traded with FTX, 80,000 hours has likely expended millions of dollars to arrive at inaccurate conclusions and accomplished exactly the opposite of their goal. I had read 80,000 hours and thought it made sense to save money that would be donated when I died. If enough people were like me, and those people trusted FTX, then 80,000 hours actually created a net negative impact on the world.
In short, if the smartest people with the most experience who spend inordinate amounts of time cannot identify scammers, then you can't either. I believe the key lesson from the past four months is that detecting cryptocurrency scams is such an intractable problem that it is not solvable with current technology. There is an unknown advancement yet to be achieved - a new blockchain feature, AI that can detect lies, a mathematical proof, some advancement in psychology or psychiatry, or something else - without which crypto lending is untenable.
Why the predictions were wrong
The next topic to ask is why my recommendations in the October and November updates didn't pan out. My best assessment right now is that what was written in regards to the companies' lending practices actually was correct, and it wasn't lending that caused the problems. Unfortunately, I can only use the publicly available information to support the last few sentences, so the remainder of this section may be unsatisfying, but I still think we can take a guess.
Let's talk about Genesis first. Many would infer from the E-Mail sent to Genesis clients about the $140m infusion that positioned Genesis for future "growth" that they were bankrupt at some point during the crisis. This message has not been posted publicly to twitter, but is shown below.
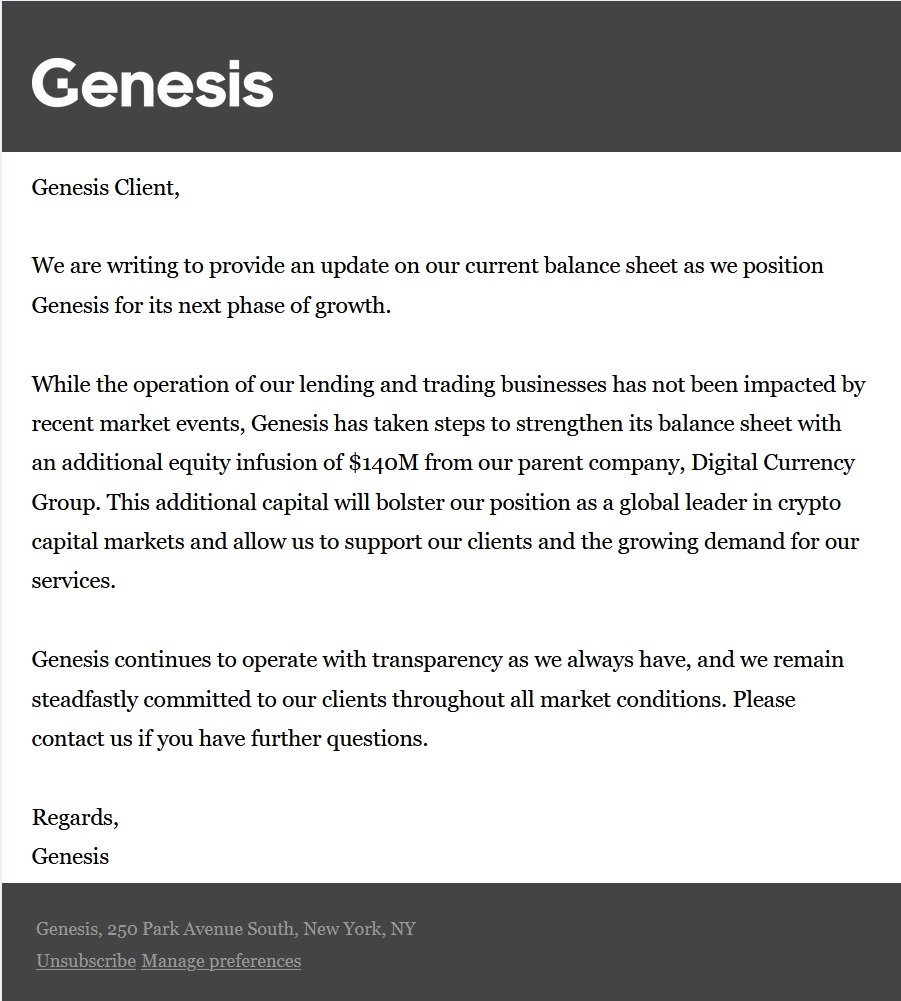
This E-Mail is one of the most understated messages in recent memory - I don't think that I need to discuss the farcical nature of it further. I had thought that Genesis had much less margin for error than BlockFi did going into the crisis, and I had assumed that the company would be the first to become insolvent because of the enormous losses they had already incurred in the previous catastrophes. It appears that was borne out. One of the only reasons that the entire cryptocurrency industry hasn't collapsed (so far) is because Digital Currency Group continues to pour money into this failing business. They likely injected funds because, as they reported on twitter, they lost $175m stored in an FTX exchange account.
From initial reports, it appears that the reason FTX.us is insolvent is because BlockFi maxed out its loans and took FTX.us and its depositors down with it. Unless BlockFi's entire uncollateralized loan book plus a third of its collateralized loans became worthless after I talked to them, which of course they might have, their failure doesn't make sense. BlockFi had a small loan book and huge member's equity, cash in the bank, money in coins with actual value, and that large loan from FTX.us they apparently did draw upon. They couldn't have lost an obscene amount like 3 Arrows or FTX did, because they simply didn't have that much money.
Therefore, something else probably occurred. One of the most common rumors spreading around is that BlockFi used FTX's "custody" product to store trading funds, and we'll find out more about that when bankruptcy is actually filed. If that is indeed the case, then the answer might be pretty simple - both BlockFi and Genesis became insolvent because they stored funds on FTX, not because of their lending practices. In military planning, what you don't know you don't know is what always comes back to haunt you. I spent 100 hours scrutinizing these companies' loan books and lending practices, and never once thought to ask where they stored money that wasn't being lent.
Another error: exchange improvements
I also made a second critical error in these reports as far back as 2020. I wrote that today's exchanges and lenders were different from Mt. Gox, in that Mt. Gox allowed production access to all of its developers and that Karpeles put most of the funds in a single hot wallet. Supposedly, today's exchanges were bound to stricter security protocols because they had learned from previous mistakes and because financial regulations were tighter.
That obviously is not true. Again, it may be that it is technologically impossible to secure a cryptocurrency exchange with current human knowledge, and that a significant advance is required to do so. Hacks are still a big problem.
But the bigger issue that I overlooked - and again, this is about not thinking to ask about something - is that these "Custody" solutions offered by Coinbase, Gemini, and Genesis can get caught up in bankruptcies. The companies are involved in lending and lots of other activities that can force them into bankruptcy as a general organization, or because of debts owed between parent and child companies. Even if you don't lose coins to the bankruptcy estate, you can still end up caught up in decades of litigation and end up being repaid in dollars.
The legal system is a fatal flaw in "custody" products, even if it were possible to create a 100% secure cold storage solution.
Dealing in bankruptcy claims
Unfortunately, because the crypto lending market has no future, and the SEC would in no way approve its applications now, BlockFi will enter Chapter 7 liquidation. The only remaining industry player who could purchase BlockFi is Binance, and even I would agree with the US government if they were to block that acquisition, as seems likely. We don't need a larger Chinese tax base that can be used to buy even more weapons to threaten Taiwan. Therefore, nobody is left, and the time to buy BlockFi was before its bankruptcy, not after the company failed and lost the faith of its customers.
Given the complexity of these cases, I doubt that any of the creditors of BlockFi will see money before 2030. However, if you want to get paid sooner, I worked with Brian Ferrera of Cherokee Acquisition on the Celsius bankruptcy case. Cherokee completed the transaction as quickly as it could, hindered only by delays that Celsius's employees created for us, and wired money a day after paperwork was signed. We earned 27.3%, exactly the amount we valued our Celsius bankruptcy claim at in the previous blog post on the topic. Given how Celsius and Voyager are likely worth far less than they were a few days ago, I'm glad I was able to remove that risk from my life - I doubt the buyer agrees, however. Ironically, all the money from Cherokee was lost paying taxes on the interest that was "earned" but not withdrawn from BlockFi.
Cherokee told me that they are monitoring BlockFi's bankruptcy and would get back to me with an offer when they have one; you can contact them as well if you are interested. They also solicited me for FTX debt. We have none, but I suppose that means they are already purchasing debt against FTX. I imagine that Cherokee will be buying debt to whatever other companies are victims of BlockFi. And while they haven't offered, I'm going to see if they would be interested in purchasing my solvent Genesis account that contains fixed term loans, so I can eliminate the risk and walk away.
Depending on Cherokee's offer, I may either take it and move on, or apply to serve on the Unsecured Creditors' Committee, since we are likely one of BlockFi's largest creditors.
Scams
For the first time ever, I am no longer 100% confident that any existing cryptocurrency will displace the legacy financial system. That is why I am currently collecting coins from lenders and wallets and unwinding my positions into the traditional banking system.
To see why, consider that in 2013, the Mt. Gox disaster resulted in losses of about a billion dollars. In 2022, there's been two events so far that will probably each result in losses greater than $100 billion to investors, depositors, and downstream collapses. FTX, as it stands right now, may be the second largest scam in the history of the world, with only Bernie Madoff surpassing it.
In December 2013, there was one exchange bankruptcy. On November 11, 2022, 134 companies filed for bankruptcy - on that single day alone.
In a "maturing" industry, scams should become less frequent over time. Instead, what we see is breathtaking exponential growth in the number of scams, hacks, and thefts. Not only are there more scams, but scams actually seem to become easier to conduct as people learn how to use the technology better. And, as I said above in regards to detecting scams, I believe that it also is not known with current technology how to prevent cryptocurrency scams. While one meltdown might be an isolated incident, things that happen again and again suggest that there is something fundamentally broken with current cryptocurrencies.
One strong candidate for what might be broken is that irreversible transactions are fundamentally incompatible with the way that human commerce works. They might be fine for computers, but the AI singularity hasn't occurred yet and humans may simply be too dishonest to work with a system that provides no recourse for fraud. Another more minor issue might be that the speed of cryptocurrency is actually a "bug" and not a feature; the slow transactions in the existing financial system (I stopped referring to it as "legacy") provide time for people to double-check what they're doing. Also, KYC and AML checks, while unpopular among enthusiasts, don't actually create problems for most people who are doing honest things.
There is no known solution to these massive crypto scams. You can't just say to "avoid centralized exchanges," because then DeFi contracts and "cross chain bridges" still get attacked. You can't solve the problem with strict regulations, because then companies just go overseas. Even if regulations worked, the irreversible nature of cryptocurrencies means that someone could still violate the regulations once and cause irreversible losses, which can't be recovered with after-the-fact penalties like jail time.
What's next
What's happened so far is only the beginning of the crisis. First, hundreds of legitimate companies with thousands of employees are going to fail as the losses from FTX and BlockFi spread. BlockFi seems to be covered as an afterthought in the mainstream media, but it would be a catastrophe in isolation. BlockFi is only small in comparison to the $9.4b that FTX lost.
We have no idea how much money Alameda Research itself lost. The $9.4b figure is how much FTX's depositors are owed. If Alameda itself was insolvent, then even more money is gone. There are probably some lenders that are owed money by Alameda but are assuming that Alameda is in better shape than FTX was.
Core Scientific will almost certainly fail now within weeks. In fact, most of the mining industry will likely go down with it. Miners moved to the United States in droves after China banned mining and took out loans from - guess who - BlockFi. With BlockFi being the main lender to mining firms, there is probably nobody now willing to extend additional credit to existing miners, even those who would otherwise survive a short downturn and which will now go bankrupt. Genesis confirmed to me that they do not offer loans to mining firms. All of these firms are now stuck under immense debt to the BlockFi bankruptcy estate, which, because it has no business relationship to save, is unlikely to be lenient to them.
All of these bankruptcies will be interconnected. At the simplest level, we have the solvent miners who owe bankrupt BlockFi. Then we have bankrupt Core Scientific which will likely owe bankrupt BlockFi a loan secured by mining rigs that need to be liquidated. More complex, we have issues like bankrupt FTX's deal to buy out bankrupt Voyager. Then there are issues potentially without precedent, like if BlockFi caused FTX.us to enter bankruptcy by drawing upon its loan, and BlockFi itself then went bankrupt because discovered it had stored money at FTX.com, and FTX.com owned part of Alameda and FTX.us, and so on and so on in a circular reference across multiple jurisdictions.
Then, imagine that a mining pool has lent all of its customers' money to BlockFi instead of some of its reserves, and had withdrawn its money from BlockFi on the last day and already paid its own customers. (PROHASHING is not bankrupt and did not do this.) Then, the mining pool's customers would end up in court fighting BlockFi's customers, with BlockFi trying to clawback money from the mining pool's customers. You can replace "mining pool" with "exchange," "lender," or whatever other business type you want to use here, because given how many creditors there are and how the worst news possible always seems to happen, there's bound to be some business that did this, pitting one group of customers against another.
And, in case you forgot, Tether - the unaudited scheme that is banned from New York, lost hundreds of millions of dollars in a fraudulent bank account, and was invested in illiquid commercial bonds - is still around.
This is the sort of future that we're living in for the next few years. Every week, there will be some catastrophe that causes more losses to ordinary people, and which beats down coin prices. There will be constant sell pressure from the bankruptcies, which will liquidate customer assets into dollars.
Then there's regulations. Regulations are in large part what got us to this point in the first place - because it remains legal to create a worthless company token or NFT pointing to an image, while illegal to create a token that actually represents something with value like company stock. Regulators punished BlockFi for unrelated issues, causing people to move funds to Celsius, and ignored Celsius, Voyager, and FTX, the latter of which had nothing to do with the BlockFi settlement but which was what actually ended up taking BlockFi down. But there will be huge numbers of regulations, which will not only make cryptocurrencies useless but also be ineffective at reducing crime because they cannot address the core weakness of irreversibility.
Finally, after all of this is done, and bitcoins are worth $9,000, and more exchanges have failed, and almost every miner is gone, and a recovery begins, the biggest problem is that there's nothing stopping this from all happening yet again. There will always be new exchanges, new coins, new tokens, and so on, and when the scams fail, people are going to lose money and prices will be beat down again. It's difficult to see how prices return to highs again when every slight rise will be defeated by whatever the newest scam is.
The future outlook
Where are we, after almost 15 years of cryptocurrency? I remember how ten years ago people said that in the near future, one would be able to walk into Wal-Mart and plug in your wallet to make a purchase. Where are those stores that accept bitcoin? Instead of assuming that they will accept it someday once there is more uptake, perhaps it's time to consider the alternate point of view - that there is a reason they are not doing so.
It's been ten years, and can anyone truly say that cryptocurrency has been a net benefit for the world? Have the isolated good deeds like a few million in donations to fight in Ukraine (many of which could have been received through other means anyway) outweighed the pain and suffering inflicted upon more than a million victims of scams and bankruptcies this year alone? How about the 50,000 people (at least) who lost jobs? Ransomware was a nearly nonexistent business before bitcoin became popular. Compare this to the banking system, where not a single person lost a single penny in a US bank account in 2021. But that's not because the FDIC or the Fed or other regulators stepped in to save depositors, it's simply because there were no bank failures that entire year!
On Friday, November 11, I held meetings with every employee and had hard discussions with them about the future of the mining business. While the $700,000 we lost in this meltdown was not sufficient to bankrupt PROHASHING or cause layoffs on its own, my concern is whether the remaining money should be invested in mining, which has an uncertain future, or whether more profit could be earned for both us and our exceptional employees by diversifying into a different industry, like cloud computing. While PROHASHING will continue to offer mining services as long as mining exists, we are currently examining whether to develop new features, or whether to focus on excellent service and uptime with the existing featureset while focusing new development outside cryptocurrency.
That said, I do believe that there will continue to be bubbles in various coins, as there have always been. I just don't think that cryptocurrency will ever become widely used by everyday humans before AI takes over the world. In a July update, I predicted that it would be 2026 until the next high. I think that the events of this Fall have likely pushed the next high to 2028. If you believe in the 4 year cycles theory, then that would be right in line with the idea that a cycle would be "skipped." People who doubt this idea should consider that the primary reason a cycle would be skipped is not because people "lost faith" in cryptocurrency - although many, like I, now believe the technology is fundamentally flawed. It's simply because so much wealth was destroyed that there is none left to buy any coins.
Storing wealth
Finally, I thought it would be worth a short section about storing wealth, because I have had this conversation multiple times with someone and we kept coming back to how insanely difficult it is to safeguard wealth.
Over the past few years, I can recall one time where I spent 100 hours writing code to crack a password on a litecoin wallet that I had written incorrectly. Then, there was money lost at multiple lenders, bank accounts that I had cancelled, exchange thefts from frauds like Graviex, the losses in value due to falls in the price of coins, the 50% losses in tech stocks, and so on. There are individual scams I dealt with that are difficult to detect, like contractor Anthony Winkelman. People who trade stocks might further recall how brokerages like Lehman Bros. and Bear Stearns can both go bankrupt and also do things like Robinhood did, allowing people to sell Gamestop stock but not buy it. Canadian teachers thought their government pensions were safe for their retirement, and now they lost $100m. Madoff's investors trusted him to manage their investments and there was no sign of trouble for decades.
My estimate is that over the past year I probably lost around $13 million. I did extremely well in life so far, and am very grateful that I managed to get what remains out when there are hundreds of thousands of people who are completely broke.
That said, I spent 70 hours a week for 14 of the last 20 years working on school and business to the exclusion of everything else, and poured money into bitcoins constantly when they were worth $200, with the plan that I would work hard for the first half of life and focus on other areas during the second half. The idea was that by collecting large sums of money, I could live off dividends and interest, and that money would then grow. Those people who are worse off than me and who are left completely broke likely did the same thing, but worked even harder. Perhaps they had worked in a factory for 20 years where they burned themselves, developed carpal tunnel syndrome, and were exposed to asbestos, then put that all of that savings into FTX.
As it turns out, no matter how much research you do, and how much work you perform, storing wealth over long periods of time is one of those intractable problems. Out of all the supposedly millions of dollars in bitcoins and other coins I owned and have lost over the past 9 years, the only non-tax transaction I ever made using coin profits was spending around $10,000 in one single instance on a TV and stereo system - that's it - less than 0.1%. After all that work, a PROHASHING employee bought a house much bigger than mine, and another bought an cool-looking new truck, while I live in a much smaller house and drive a car that's 13 years older.
No matter how hard you try, it's extraordinarily easy to lose enormous amounts of money with single mistakes, and yet it's extraordinarily difficult to gain money even with enormous amounts of effort. I'm not going to spend the next 20 years saving up when it could easily be lost in the next financial crisis. Starting when I get back to work next week, I plan to spend almost all of the money I earn as I make it. People make it sound as if buying a car is a bad financial decision, but my car hasn't gotten lost in 16 years, and I have used that home theater every night for the past year. You might consider spending more of your money too.
Conclusions
Here are my conclusions:
- Withdraw money from all exchanges, lenders, and "custody" providers to cold storage as soon as possible. There are more failures coming. The earlier you withdraw, the earlier the clawback window expires in February.
- The crypto lending market is not profitable. None of the companies in the lending industry have actually made any money. The survivors like Genesis have lost billions of dollars and are surviving only with the help of their parent firms. I don't trust what any of these people are saying, and in most cases, they're not at fault because they don't know what is going on themselves. At some point these CEOs are going to give up and realize that you can't make money operating a crypto lending business.
- Unlike the previous 3 Arrows crash, this situation is not going to just "blow over" and return to business as usual. The crypto lending market is dead. The technology and knowledge does not yet exist for people to have an accurate-enough method of detecting scams and calculating risk in cryptocurrencies. Don't get suckered back in by new companies that will inevitably pop up in a few months claiming that they "learned" and are doing safer things. After all, that's what they told me the last time.
What happened this week is fundamentally different than the typical "China bans bitcoin" or "Elon Musk says he likes dogecoin over bitcoin" nonsense that has caused past panics. There is a genuine possibility that today's cryptocurrencies have showstopping flaws that will ever prevent wide use in commerce. Regulations may additionally restrict cryptocurrency usage and cause the next panic. Consider going further like I have and liquidating cryptocurrencies to dollars (not stablecoins) until the bankruptcies stabilize and a yet-unknown advance occurs that can genuinely mitigate the scams and hacks problem.
While I will continue to blog about other topics, including cryptocurrency topics, this will be the final update I post on the topic of crypto interest. Keep following PROHASHING, and we'll definitely be sharing whatever new venture we decide to create outside of cryptocurrencies within a few months!
Comments (0)
Archived discussion. New comments and replies are closed.
No archived comments on this article.